
Month-end flows, mega-cap tech earnings, war headlines roulette, and central bank decisions served to create a dynamic trading backdrop this week.

Chart Source(s): Fundstrat, Bloomberg
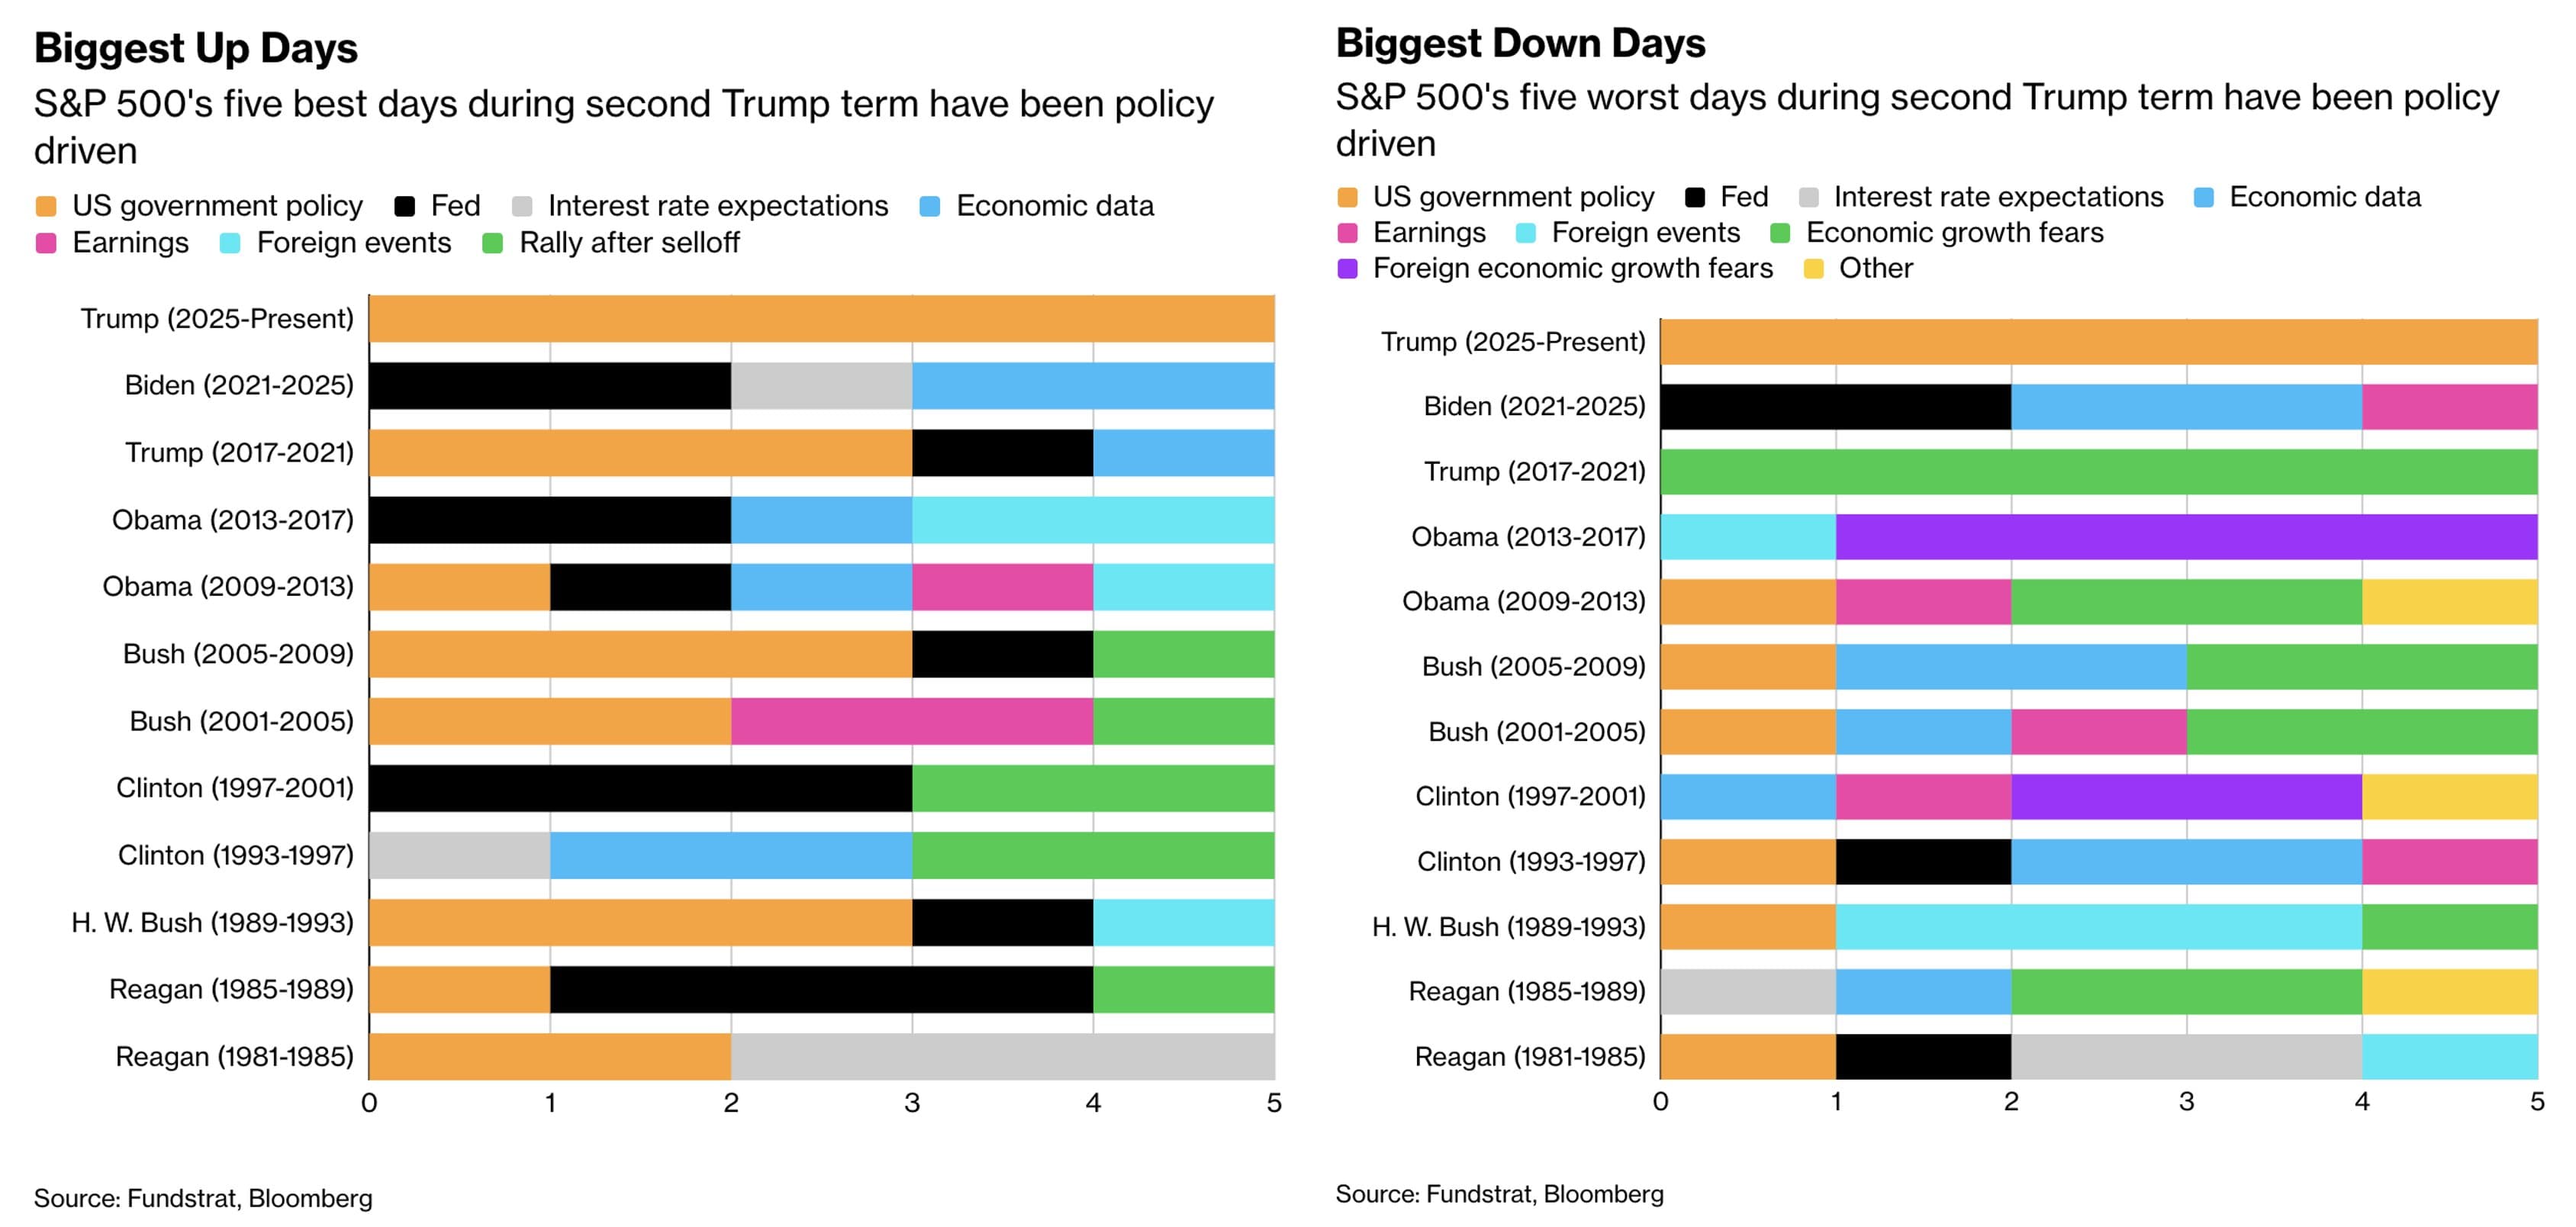
If it feels like an oppressive version of Groundhog Day in the markets for the past 466 days, then you are not imagining things. The statistics demonstrate that Trump’s second term in office has unleashed nothing short of chaos on day-to-day price action.
Global Markets & Economic Data
- US: The Fed kept rates on hold and remarks were hawkish leading the market to price no cuts in 2026. Initial Q1 GDP estimates are 2% y/y growth.
- Switzerland/UK/EU: Swiss KOF leading indicators recovered in April from a 9-month low registered in March. The BoE decided to keep interest rates on hold at 3.75% and members were leaning hawkish for future decisions. Similarly the ECB remained on hold at 2.15%. German consumer confidence hit the weakest level in 3-years amid 2.9% annualized inflation numbers in April, jumping from 1.9% in February. Germany’s initial Q1 GDP estimate is a 0.3% y/y growth and the EU Area Q1 estimate is 0.8%.
- China/Japan: The BoJ kept rates on hold at 0.75% and some members wanted to hike to 1%. Chinese March Manufacturing PMIs expanded at the fastest pace since 2020.