
March 20th, 2026

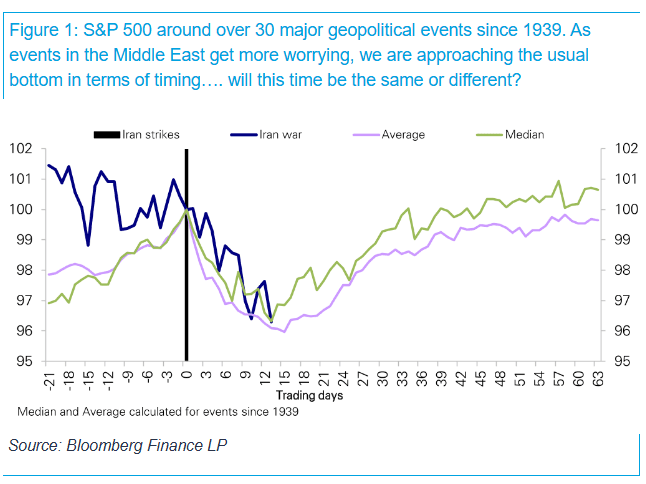
Chart Source(s): Bloomberg Finance LP
Deutsche Bank analysts put together some interesting analysis this week on war’s impact on the S&P 500. Good news, according to their analysis of 30 past war events, the S&P 500 bottoms T+15 days post war onset at just around the -4% level where we stand today.
While historical statistics can be comforting, every situation is different and clearly there are many open-ended issues at play here before the all clear flag is waived. In the meantime, hedge fund PMs are opting on de-risking as the best path forward as many typical risk-off hedges (bonds, precious metals, equity puts) are proving elusive.
Risk continues to trade heavy with pockets of intermittent bursts of optimism. Central banks were unanimously on hold with a hawkish bent this week.
Global Markets & Economic Data
- US: February pre-war PPI was hotter than forecast rising 0.7% versus 0.3% expected. The Fed held rates unchanged, and Powell’s speech was considered hawkish. US housing activity remains subdued.
- Switzerland/UK/EU: Switzerland’s trade surplus widened, driven by a fall in imports. Watch exports are on a 5-month uptrend. The SNB, BoE & ECB held rates unchanged. The UK Unemployment Rate is at multi-year highs of 5.2%. Germany’s ZEW Economic Sentiment index crashed due to a war-related spike in energy prices.
- China/Japan: Chinese Industrial Production surged 6.3% y/y. Chinese YTD FDI remains negative y/y, but high-tech industries are seeing a 20.4% y/y surge. The BoJ held rates unchanged.
Market Spotlight: Europe in the crosshairs
The case for a continued uptrend in European growth hinges upon a stable energy supply backdrop. Sadly, Europe finds itself in the middle of the Iranian conflict despite never agreeing to take part.

Chart Source(s): tradingeconomics.com | Centre for European Economic Research (ZEW)
Market Spotlight: Corporate catalysts in Japan
Public activist campaigns in Japan reportedly rose nearly 90% from 2024 to 2025, making Japan the second most active market globally after the U.S.

Chart Source(s): JP Morgan | FactSet
Our team is ready to provide further insights into our strategies and the current market landscape. Reach out to us today.
Disclaimer: This material has been prepared by MASTERPIECE ADVISORS for informational purposes only and should not be construed as financial advice. Investments in hedge funds are speculative and involve a high degree of risk. This material is confidential and may not be disclosed without the express written approval of MASTERPIECE ADVISORS.