
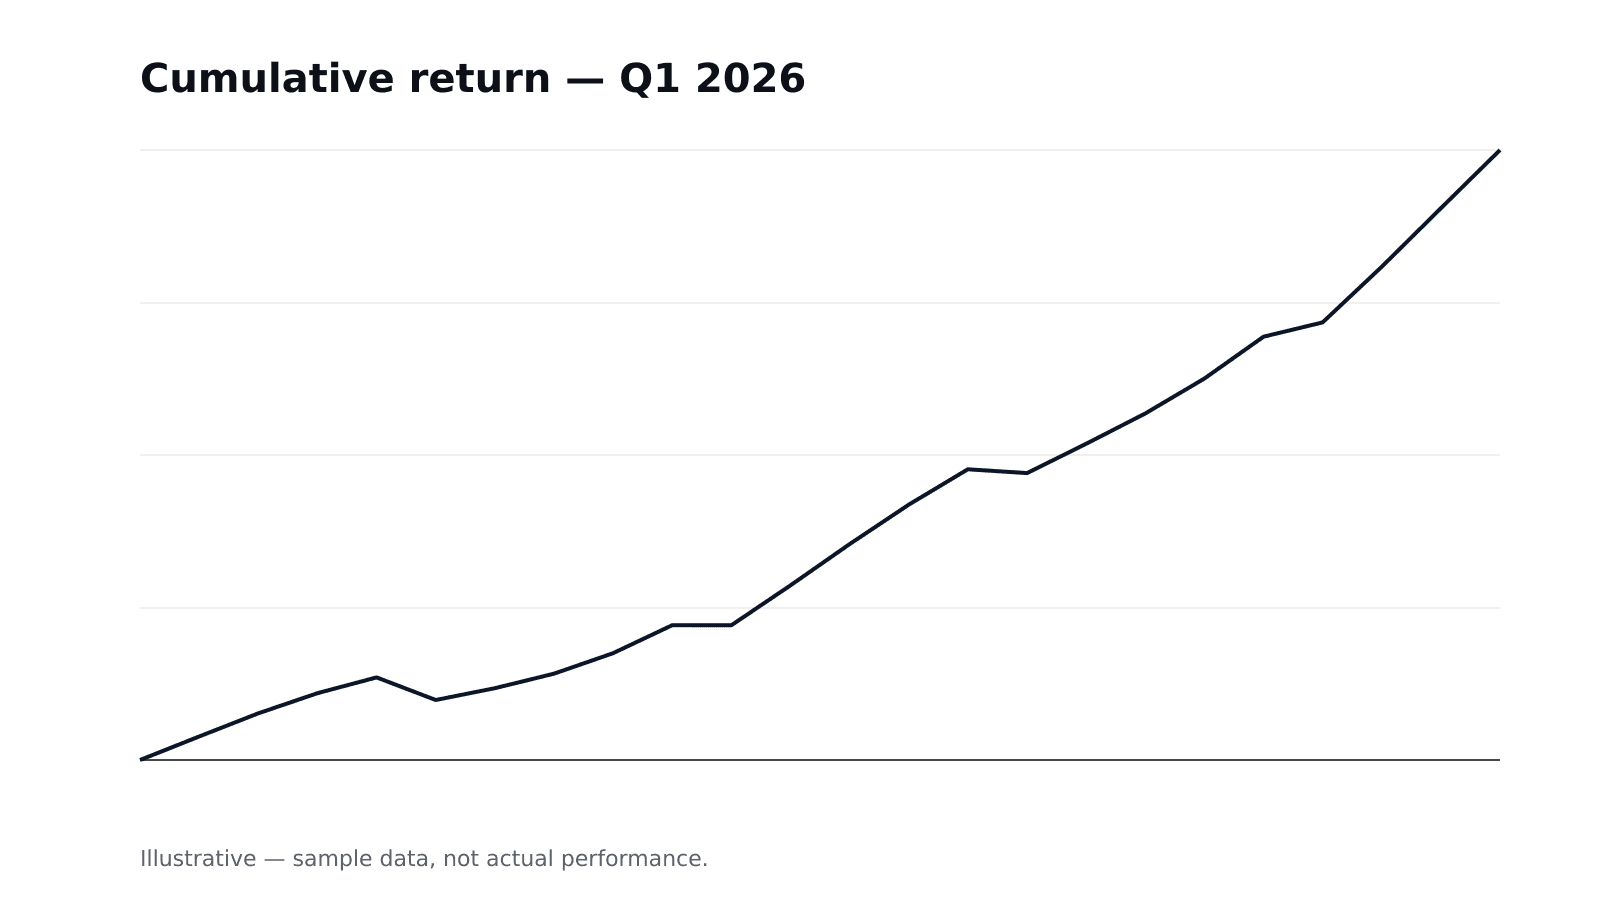
Risk assets extended their recovery through the quarter, with dispersion across strategies widening into March. The cumulative path below is illustrative of a representative low-net book.

Contribution was led by global macro and long/short equity, with credit detracting modestly. We continue to favour managers whose alpha does not depend on directional beta.