
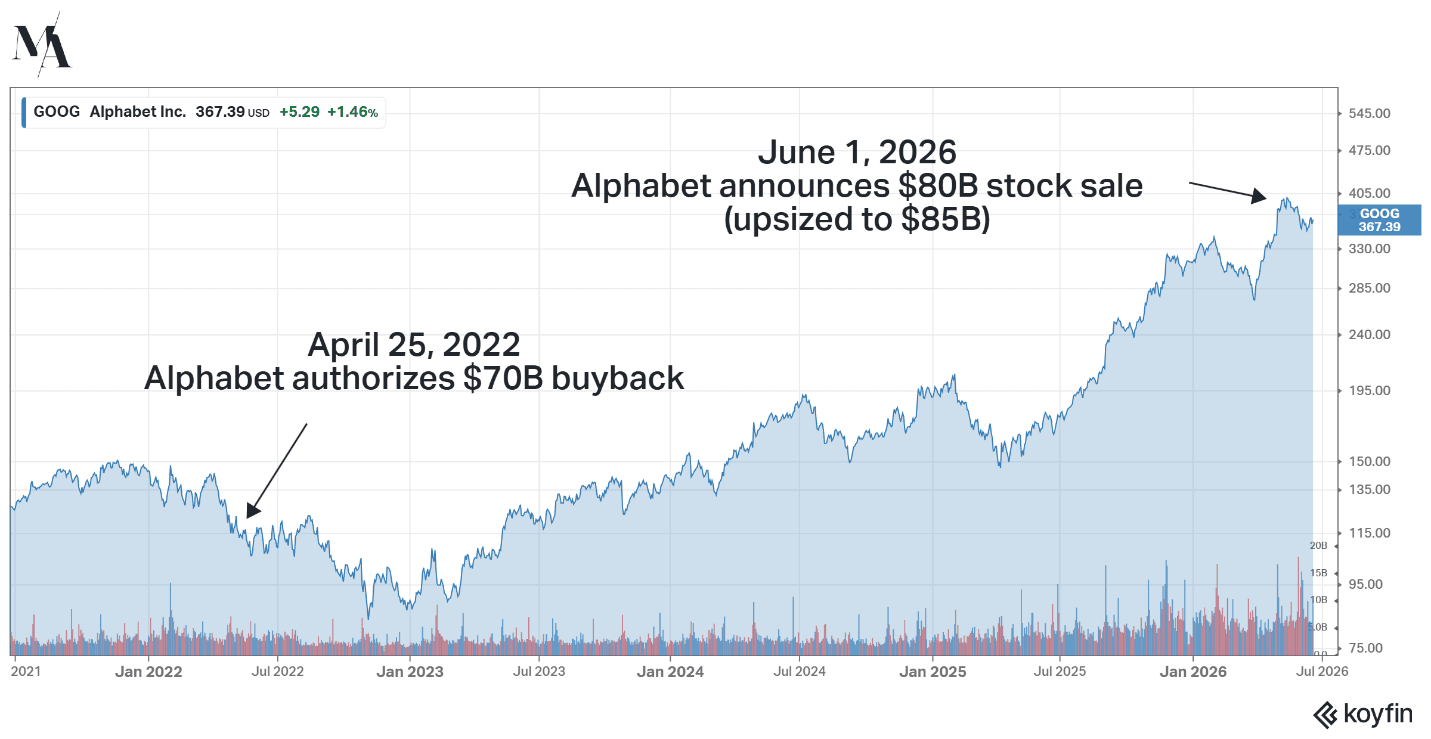
Price action continues to signal a market celebrating peace and prosperity with unusual fervor as volatility is quashed and risk is sportingly embraced.
Alphabet’s $85b equity raise came as a bit of a shock given hyperscalers have traditionally been far more inclined to buyback stock rather than sell more.
The developments raise another yellow flag of concern over the general state of the markets, which seems to be moving onto an even more speculative phase of this bull market.
How far the speculation goes from here remains an outstanding debate among investors, but one thing is certain; they don’t necessarily ring a bell at the top, but they sure sell a lot of stock.
Global Markets & Economic Data
- US: The Fed kept interest rates on hold and communication was viewed as hawkish. Housing starts in May fell to the lowest level since May 2020.
- Switzerland/UK/EU: The SNB held interest rates at 0% as expected and signaled their willingness to continue to intervene to quell CHF strength. UK inflation rose by 2.8% y/y in May, below the 3-3.1% forecast and the unemployment rate was slightly below forecast at 4.9%. Recent European sentiment figures surged after slumping for three consecutive months.
- Japan/China: The BoJ hiked interest rates by 25bps to 1%, in-line with expectations. Chinese retail sales figures were below expectations, falling m/m in May.
Index Returns Summary
- MSCI World: -1.51% MTD · 9.20% YTD
- MSCI Asia Pacific: -1.97% MTD · 12.41% YTD
- MSCI Europe: 0.51% MTD · 7.81% YTD
- Bloomberg Barclays Global Aggregate Index: -0.49% MTD · 0.03% YTD
- Bloomberg Commodities Index: -4.20% MTD · 19.06% YTD
- HFRX Global: -0.16% MTD · 3.98% YTD
- HFRX Macro/CTA: -0.80% MTD · 5.85% YTD
- HFRX Equity Hedge: -0.32% MTD · 6.53% YTD
Index data as of June 12, 2026